
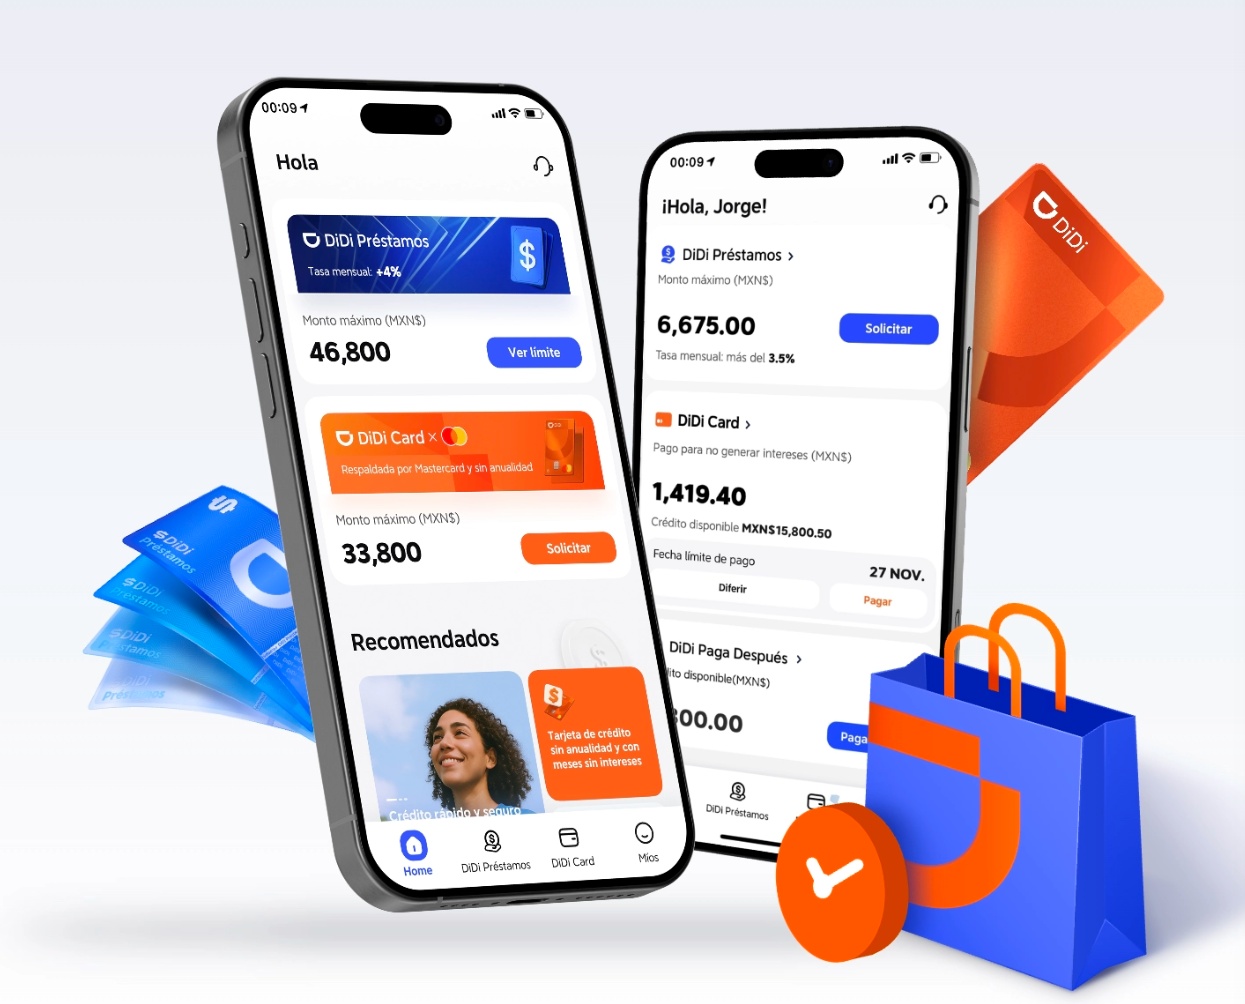
I started messin’ with this whole buy-now-pay-later idea down in Mexico City after the lockdowns, and lemme tell ya — it ain’t all bells and whistles. Folks around me were using it for groceries and bike repairs, and the app that kept comin’ up was didi finanzas. For a plain-spoken user, the promise is clear: break payments into easy installments, skip big upfront hits, and keep the household ship steady. The user onboarding in the didi finanzas app felt simple — quick verification, merchant integration that worked, and a short rundown of any fees or credit line limits.
What Buy Now, Pay Later Actually Does for You
This here service lets you split a purchase into equal installments over a few weeks or months. It ain’t magic; it’s practical. Installments reduce the immediate cash drain. Merchant integration means stores can offer the option at checkout. For many working folks, that small time-shiftin’ of payments can stop payday scrambles and give breathing room without takin’ on a traditional credit card balance.
User Benefits That Matter Day-to-Day
Look for these plain benefits when you try BNPL through DiDi:
– Smaller monthly outlay: spreads cost across several payments so bills don’t pile up fast.
– Faster approval: less paperwork than a bank loan; most approvals hinge on basic identity checks.
– Built-in reminders: the app often sends push notifications for upcoming due dates, so you don’t forget.
Where Folks Trip Up — and How to Dodge It
Some mistakes show up again and again. People skip readin’ the terms, overlook late fees, or treat BNPL like free credit. That’ll bite you — missed payments can add fees and harm your credit line access. Also, not every merchant offers the same plan; one store might have interest-free installments, another might charge an interest rate on longer terms.
Be mindful of the difference between zero-interest offers and deferred-interest plans — they sound alike but act different. Set calendar alerts. Keep purchases modest enough that the sum of installments fits the household ledger. — And remember: repeat small buys can add up quicker than a surprise repair bill.
Comparing DiDi’s Option with Other Choices
BNPL sits between cash and credit cards. Compared to a credit card, the user experience tends to be simpler: shorter user onboarding, clearer installment cycles, and sometimes lower sticking fees. Compared to payday loans or short-term credit, BNPL typically carries lower cost — provided you pay on time. If you’re weighing alternatives, check APR, late-fee structure, and how each one reports to credit bureaus.
How to Use It Smartly — Practical Steps
Start small. Use BNPL for a single predictable purchase first, like a phone repair or a set of tires. Confirm the installment schedule, any interest rate, and the merchant integration details before you tap ‘confirm.’ Keep receipts and screenshots of the plan. If the app offers budgeting tools or a payment calendar, use ’em — they save headaches later.
Three Golden Rules for Pickin’ the Right Way
When choosin’ services like this, weigh these three metrics every time:
1) Total cost of credit — add up all installments plus any interest or fees to see the real price.
2) Repayment clarity — check the payment schedule and the consequences for late payments.
3) Reporting and limits — know whether missed payments affect your credit and what your credit line looks like for future needs.
I’ve seen neighbors switch to BNPL and steady their monthly flow; others who ignored rules learned the hard way. If you want a down-home tool that smooths cash flow and keeps bills predictable, DiDi Finanzas fits right into that middle ground where smart folks steady their spending — DiDi Finanzas. —