
Why quick loans can actually help you—if you use them right
Think of short-term online loans as a tool, not a trap. For many folks juggling rent, car repairs, or a sudden travel need, a smooth, pre-approved option can be a lifesaver—especially in cities like Mexico City where commuters relied on mobile apps during the 2020 lockdowns. Start by checking the offer’s APR and how that APR translates into monthly installments. If you want to compare a few options fast, look up a few providers and test eligibility—didi prestamos is one of the places people try first because of its quick pre-approval flow and straightforward terms.
Numbers you can control before you hit “apply”
Focus on the few metrics that make the biggest difference: effective interest rate, loan term, and fees. Keep these steps in your pocket:- Run a quick credit score check so you know where you stand.- Compare the total repayment amount, not just the monthly payment.- Look for early repayment rules or origination fees.These actions lower surprises and turn a rushed decision into a strategic move. Underwriting can be fast, but it still uses those inputs—so tidy them up first.
How DiDi Finanzas fits into a real-life plan
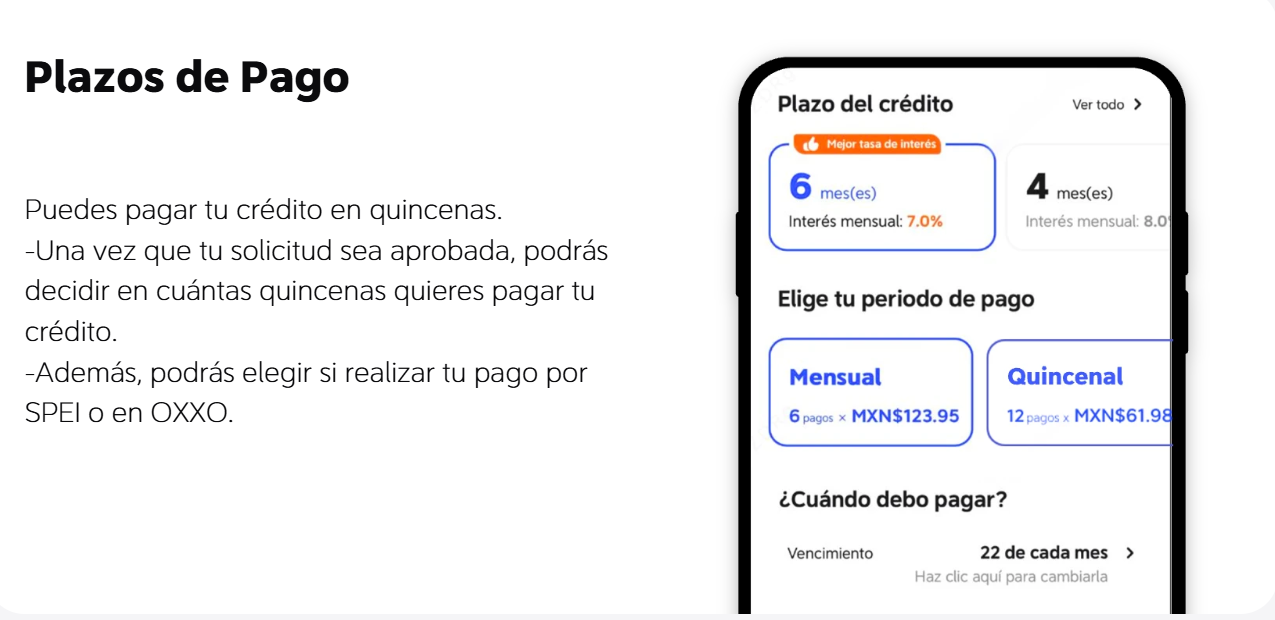
From a user point of view, platforms that pair fast approvals with clear repayment schedules win. In my own run-in with a car breakdown, I needed cash the same day—so I tried a few apps and found the interface and installment options on didi credito straightforward. The app showed the interest rate, total cost, and a digital wallet option for repayments, which let me schedule payments without missing one. That hands-on clarity saved me from a guesswork rollover—or worse, multiple small loans.
Common mistakes people make and how to avoid them
One: assuming a lower monthly payment always means a better deal. Two: skipping the fine print on late fees or how many installments you can miss before penalties apply. Three: chasing multiple small loans at once—this can spike your credit score inquiries and hurt future terms. Fix these by prioritizing total cost, checking grace periods, and keeping a single active short-term loan whenever possible. A short pause to read the terms pays off.
Quick checklist to squeeze the most benefit
Use this step-by-step when you’re ready:- Confirm your credit score and recent inquiries.- Pick the shortest reasonable term that keeps monthly installments manageable.- Opt for automatic payments if there’s no hidden fee.- Save screenshots of the loan contract and payment schedule.These small moves cut friction and reduce accidental late fees—so you actually save money, not just buy time.
Picking between alternatives
Compare banks, fintech apps, and employer-linked programs. Banks might offer lower interest but slower funding. Fintechs usually give speed and a smoother UX, but watch for fees. Employer-linked advances can be cheapest but may affect payroll. Balance speed, cost, and invisibility to future creditors depending on whether you need cash now or a reliable borrowing history later.
Advisory: three golden rules before you commit
1) Evaluate total cost: prioritize the total repayment amount and APR over the headline monthly payment. 2) Protect cash flow: choose a term where monthly installments stay comfortably below 25–30% of your net income. 3) Preserve credit options: avoid multiple small loans that raise hard inquiries and limit your ability to refinance later.
Real results come from disciplined choices and clear numbers. DiDi Finanzas fits naturally when speed, transparency, and scheduled repayments are the solution. —